

Top Security Companies in Sydney (48)
Atlassian creates teamwork solutions for high-performing teams. Our portfolio of collaboration and work management software products includes Jira, Confluence, Trello, Loom and Rovo. More than 300,000 businesses worldwide rely on Atlassian’s technology, including 80 percent of Fortune 500 companies. Our solutions support various business teams and they help organizations plan, track, and deliver their biggest ideas together.
Atlassian's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is expanding at strong double‑digit rates across recent quarters and the latest fiscal year, with cloud revenue and ARR also rising. Investor materials and quarterly updates highlight consistent momentum rather than a one‑off spike.
Strong Market Position & Advantage: Independent analyst recognitions position the company as a Leader across multiple core categories, and it serves a very large, global customer base including much of the Fortune 500. This broad market presence supports pricing power, cross‑sell, and durable demand.
Innovation-Driven Growth: Cloud migrations and newly introduced AI capabilities are cited as meaningful tailwinds for adoption and expansion. Product enhancements and platform integrations are associated with larger enterprise deals and a growing backlog of committed revenue.
CrowdStrike has redefined security with the world’s most advanced cloud-native platform that protects and enables the people, processes and technologies that drive modern enterprise. Tested and proven, the world's largest organizations trust CrowdStrike to stop breaches with unparalleled protection against the most sophisticated cyberattacks. The CrowdStrike culture has been built upon our Core Values since the day we began. We...
CrowdStrike's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue and annual recurring revenue are increasing at a robust pace, with recent quarters showing re-acceleration and a raised full‑year outlook. This momentum is supported by record net new recurring business and continued customer and module expansion.
Healthy Cash Flow: Operating and free cash flow are at record levels for recent periods, underscoring strong cash generation alongside growth. Liquidity is reinforced by scaling cash from operations as the platform expands.
Profitability: GAAP profitability has improved from prior losses to positive territory, with operating leverage trending upward. This shift indicates improving economics as scale increases.
Snyk, the leader in secure AI software development, empowers organizations to build fast and stay secure by unleashing developer productivity and reducing business risk. The company’s AI Trust Platform seamlessly integrates into developer and security workflows to accelerate secure software delivery in the AI Era. Snyk delivers trusted, actionable insights and automated remediation, enabling modern organizations to innovate without limits....
Snyk's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Revenue and ARR continued to rise, with ARR surpassing $300M by 2025 and revenue increasing in 2024. Feedback suggests growth has moderated from earlier hypergrowth into a steadier, efficiency‑focused trajectory while the customer base expanded to 4,500+.
Product Line Growth: Snyk Code reached $100M in ARR and newer offerings such as DAST and AI‑focused products (e.g., Evo) showed strong momentum. These developments indicate the platform is extending beyond its original core into additional security categories.
Market Expansion: Enterprise adoption intensified, with that segment driving a large share of new additions and AI security opening fresh routes to demand. Customer counts grew materially from 2024 into 2025, signaling broader market reach.
Zscaler accelerates digital transformation so our customers can be more agile, efficient, resilient, and secure. Our cloud native Zero Trust Exchange platform protects thousands of customers from cyberattacks and data loss by securely connecting users, devices, and applications in any location.

Zscaler's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising from $1.62B in FY2023 to $2.17B in FY2024, $2.67B in FY2025, and about $3.35B in FY2026, with Q4 FY2026 up 25% year over year. This trajectory, alongside mid‑20% ARR growth, indicates continued expansion rather than a stall.
Healthy Cash Flow: Cash generation is growing, with free cash flow rising to about $779M in FY2026 and a free‑cash‑flow margin near 23%. Non‑GAAP operating metrics, including an ~80% gross margin, underscore operating leverage.
Strong Market Position & Advantage: Industry evaluations list the company as a Leader in the 2026 Gartner Magic Quadrants for both SSE and SASE, with five consecutive years of SSE leadership. Expanding large‑enterprise adoption and thousands of customers support a durable position in its core zero trust/SSE markets.

Thales is a global high technology leader investing in digital and “deep tech” innovations – connectivity, big data, artificial intelligence, cybersecurity and quantum technology – to build a future we can all trust, which is vital to the development of our societies. The company provides solutions, services and products that help its customers – businesses, organisations and states – in...
Thales's Top Stability & Growth Strengths
Strong Revenue Growth: Sales increased in 2025 versus 2024, with early 2026 also showing higher sales and management guiding to further organic growth in 2026.
Profitability: Adjusted EBIT rose and margins improved in 2025, indicating strengthening operating performance alongside growth.
Resilient & Sustainable Growth: Record order intake and an order book above €53 billion provide multi‑year visibility, and a book‑to‑bill above 1 with reaffirmed 2026 targets supports continued expansion.
DroneShield is a global leader in counter-UAS security and technology, specializing in AI-powered, multi-mission solutions that protect military, government, law enforcement, and critical infrastructure from unmanned system threats. The company leverages RF sensing, artificial intelligence, sensor fusion, and electronic warfare to provide comprehensive detection and defeat solutions across air, ground, and maritime domains.

Verkada is the world’s largest cloud-based B2B physical security platform, offering a seamless blend of tech and safety. With six product lines — video security cameras, access control, environmental sensors, alarms, workplace systems, and intercoms — all integrated on one cloud platform, Verkada is designed for simplicity and scalability. Our real-time insights help organizations keep their spaces safe and comfortable...
Verkada Inc's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as rising markedly year over year, with estimates indicating substantial topline expansion from earlier periods through the most recent fiscal year. Customer and device counts also grew materially, reinforcing momentum at scale.
Investor Backing & Capital Strength: Successive late‑stage financings, including an investment led by CapitalG at a multi‑billion valuation and a strategic tie‑up with NVIDIA, point to strong external support. Increased valuations and significant capital provide resources to fund product development and geographic expansion.
Strong Market Position & Advantage: Independent rankings place the company at the top of VSaaS and cloud access control, underscoring leadership within cloud‑native physical security. A unified, AI‑driven platform and a large, diversified enterprise customer base reinforce this position.
Imperva is a cybersecurity leader with a mission to protect data and all paths to it. We protect the data of over 6,000 global customers from cyber attacks through all stages of their digital transformation. Our products are informed by the Imperva Research Lab, a global threat intelligence community, that feeds the latest security and compliance expertise into our solutions.

MSS Security is a leading Australian provider of security and emergency response services, protecting critical infrastructure and high-profile clients across all market segments.
MSS Security's Top Stability & Growth Strengths
Strong Market Position & Advantage: National coverage across every Australian state and territory, large-account capability, and broad sector reach position MSS as a major provider with substantial operating scale. Business-directory profiles citing significant market share and thousands of employees reinforce a durable competitive footing.
Strong Hiring & Retention: Headcount is described as growing from 6,000+ to more than 8,000, with ongoing recruitment and expanded in-house training capacity. Approval to deliver a transport-security qualification supports onboarding and workforce development at scale.
Investor Backing & Capital Strength: Ownership by SIS Limited provides access to a larger international platform, resources, and expertise that can support expansion. Corporate materials highlight the parent’s scale, indicating capacity to invest in Australian growth.


Plerion is an all-in-one Cloud Security Platform that supports workloads across AWS, Azure, and GCP delivering cloud security posture management, workload security, data security, IAM security, continuous compliance, software bill of materials, shift left security, and more.

Kroll is the world’s premier provider of services and digital products related to valuation, governance, risk and transparency. We work with clients across diverse sectors in the areas of valuation, expert services, investigations, cyber security, corporate finance, restructuring, legal and business solutions, data analytics and regulatory compliance. Our firm has nearly 5,000 professionals in 30 countries and territories around the...
Kroll's Top Stability & Growth Strengths
Strong Market Position & Advantage: Multiple third-party descriptions and industry recognitions portray Kroll as a leading independent provider in financial and risk advisory, with top placements in areas like fairness opinions and investigations/forensics. Scale signals such as a global workforce and long operating history reinforce a durable competitive position.
Market Expansion: Evidence points to active expansion through new practices (e.g., Economics and Decision Intelligence), geographic build-outs, and acquisitions across regions including APAC, Europe, and Latin America. Announcements of added services and locations indicate an expanding footprint.
Diversified Revenue Streams: A broad portfolio spanning valuation, investigations, due diligence, compliance, cyber/MDR/IR, restructuring, and agency/trustee services suggests multiple demand drivers. Recognition across several distinct service lines implies revenue is not dependent on a single offering.
UpGuard combines third-party security ratings, vendor questionnaires, and threat intelligence capabilities for a complete cyber risk solution.
Customer Focus, Innovation and Purpose are Built Into Everything We Do. Lockheed Martin. Your Mission is Ours ™. Headquartered in Bethesda, Maryland, Lockheed Martin is a global security and aerospace company principally engaged in the research, design, development, manufacture, integration and sustainment of advanced technology systems, products and services.
Lockheed Martin's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent rankings place the company at No. 1 globally and it leads major air and missile defense portfolios such as Aegis BMD and PAC‑3, reinforcing competitive advantage. Broad adoption of the F‑35 and leadership across four large segments further underpin its position.
Resilient & Sustainable Growth: A record ~$193.6–$194B backlog provides multi‑year revenue visibility across segments. Multi‑year munitions frameworks and planned PAC‑3 production ramps point to sustained demand.
Strong Revenue Growth: Sales rose 6% in 2025 to $75.0B, with segments like Missiles & Fire Control and Aeronautics expanding and guidance indicating further top‑line growth in 2026. Record F‑35 deliveries and new missile/space milestones contribute to the outlook.
Bugcrowd is the #1 crowdsourced security platform. More enterprise organizations trust Bugcrowd to manage their bug bounty, vulnerability disclosure, attack surface management and next-gen pen test programs. By combining the largest, most experienced triage team with the most trusted hackers around the world, Bugcrowd generates better results, reduces risk through remediation advice, and empowers organisations to release secure products to...
Relentless protection. Resilient world. Mimecast (NASDAQ: MIME) was born in 2003 with a focus on delivering relentless protection. Each day, we take on cyber disruption for our tens of thousands of customers around the globe; always putting them first, and never giving up on tackling their biggest security challenges together. We are the company that built an intentional and scalable design...
Mimecast's Top Stability & Growth Strengths
Strong Market Position & Advantage: Mimecast is positioned as a leader in email security platforms, supported by repeated Gartner Magic Quadrant Leader placements and a large global customer footprint. The scale of threat processing and breadth of security, archiving, and continuity capabilities reinforce competitive advantage in its core market.
Strong Revenue Growth: Revenue is described as increasing year-over-year through fiscal 2025, with references to record new and expansion revenue gains. Projected net income growth into 2026 is presented as an additional indicator of strengthening financial momentum.
Product Line Growth: The platform is expanding beyond email security into human risk management, insider risk, and collaboration security via acquisitions such as Elevate Security, Code42, and Aware. Ongoing launches like Cloud Integrated Email Security and expanded modules (e.g., DMARC tools, add-ons for archiving/continuity) indicate continued portfolio broadening.
Fueled by a belief that identity professionals deserve better, we found a way to break down the silos of identity security—eliminating the gaps and blind spots left behind by a patchwork of point solutions. The Silverfort Identity Security Platform is the first to deliver end-to-end identity security, protecting every identity in the cloud, on-prem, humans, machines, and everything in between....
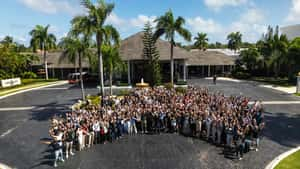
Silverfort's Top Stability & Growth Strengths
Strong Revenue Growth: Feedback suggests revenue expanded rapidly, with repeated statements of 100%+ year-over-year growth and tens of millions in new ARR, alongside steady additions of 100+ enterprise customers quarterly.
Investor Backing & Capital Strength: Feedback suggests a $116M Series D in January 2024 raised total funding to $222M at a roughly $1B valuation, supporting platform expansion and accelerated go-to-market.
Strategic Partnerships: Feedback suggests alliances with Microsoft, SentinelOne, Google Cloud, and other ecosystem partners broaden technical integrations and go-to-market reach.
Vectra® is the leader in threat detection and response – from cloud and data center workloads to user and IoT devices. Its Cognito® platform accelerates threat detection and investigation using AI to enrich network metadata it collects and stores with the right context to detect, hunt and investigate known and unknown threats in real time. Vectra offers four applications on...

At Payatu we believe in following one’s passion and with that thought, we have created a world class team of researchers and executors who are bending the rules to provide state of the art security services. Recognized by Great Place to Work (India) as an amazing workplace. We are a passionate bunch of folks working on the latest and leading...
Cubic Corporation (Cubic) is an international provider of systems and solutions that address the mass transit and global defense markets.

Cubic Corporation's Top Stability & Growth Strengths
Strong Market Position & Advantage: Cubic is repeatedly characterized as a leader in large-scale transit fare collection and as the de facto standard in live air-combat training instrumentation, supported by marquee deployments (e.g., OMNY, Ventra, Opal) and widespread P5CTS fielding. Sole‑source upgrades and longstanding roles on flagship systems reinforce durable competitive advantages in its two core niches.
Market Expansion: Recent awards in both segments—such as USAF IDIQs for additional P5 pods and security upgrades, plus transit wins like SEPTA Key 2.0, OMNY equipment extensions, PATH, and Tasmania—show a growing footprint and multi‑year workload visibility. Product moves like Open Payments on Umo extend fare technology into mid‑sized agencies, broadening the addressable market.
Investor Backing & Capital Strength: A 2025 recapitalization added new liquidity and equity support from sponsors, reduced debt, extended maturities, and targeted substantial interest savings. In early 2026, an upgrade from selective default to CCC‑ with positive CreditWatch followed a deferred interest arrangement, signaling some near‑term financial relief.
Check Point Software Technologies Ltd. (www.checkpoint.com) is a leading provider of cyber security solutions to governments and corporate enterprises globally. Check Point’s solutions protect customers from 5th generation cyber-attacks with an industry leading catch rate of malware, ransomware and advanced targeted threats. Check Point offers a multilevel security architecture, “Infinity Total Protection with Gen V advanced threat prevention”, this combined...
Check Point Software Technologies, Ltd.'s Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent analyst evaluations across 2024–2025 consistently place Check Point in the Leaders cohort for enterprise and hybrid‑mesh firewalls and also in email security. Trade coverage and third‑party testing corroborate top‑tier firewall efficacy and broad recognition.
Profitability: Non‑GAAP EPS expanded strongly in 2025 and continued to grow in early 2026, indicating margin strength alongside the subscription mix shift. Company updates highlight sustained earnings momentum despite uneven hardware demand.
Healthy Cash Flow: Recent periods show rising operating cash generation and higher adjusted free cash flow, with ongoing share repurchases signaling capacity for capital returns. Cash performance has remained solid through FY2025 and into 2026.



